Your budget may not be the problem
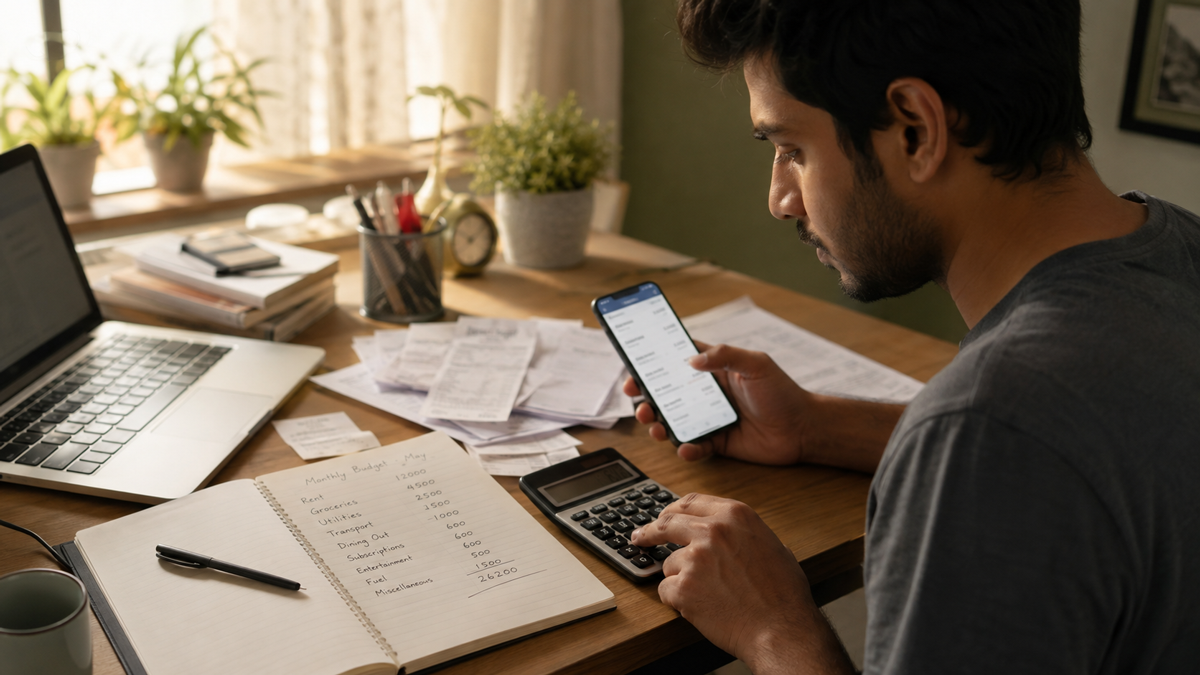
You made the spreadsheet, assigned every rupee a job and promised yourself this month would be different. Then the last week arrives and your account balance is already uncomfortable.
That does not automatically mean you lack discipline. A budget can fail because the numbers were never realistic, irregular expenses were missing, or the plan left no room for normal life.
A budget is a forecast, not a promise
If you write ₹8,000 for groceries, you have not made groceries cost ₹8,000. You have made a prediction. The useful question is whether that prediction came from actual spending data.
Pull the last two or three months of transactions and compare what you planned with what you really spent. The gap is valuable information. A budget becomes stronger when it learns from reality instead of forcing reality to match an old spreadsheet.
The expenses that appear “out of nowhere”
Annual insurance, festivals, birthdays, repairs, medical bills, school costs and travel are not random just because they do not happen every month. If you know they are likely to happen sometime during the year, they belong somewhere in the plan.
Create sinking funds for predictable irregular costs. Divide an annual expense into monthly contributions so the month of payment does not feel like a financial emergency.
Variable spending needs attention
Food delivery, transport, shopping and social spending can change dramatically from week to week. Looking only at a monthly total hides the pattern.
Instead of saying “I spent too much,” identify the category that repeatedly runs over. That gives you something specific to change.
Leave breathing room
A budget that assigns every rupee to a fixed category can be mathematically neat and practically fragile. A small buffer gives ordinary surprises somewhere to go without forcing you to borrow from another category.
A buffer is not an excuse to spend more. It is protection against pretending every month will behave exactly like the last one.
Rebuild the budget from actuals
- Review the last 2–3 months of transactions.
2. Categorise variable spending.
3. Add known irregular expenses as sinking funds.
4. Add a realistic buffer.
5. Set category limits from your actual pattern, not your ideal behaviour.
6. Review the budget whenever income or routine changes.
The goal is not a stricter budget
A budget that constantly makes you feel guilty is difficult to maintain. A useful budget should tell you where your money is going, what is coming up, and how much flexibility you actually have.
If you keep running out of money, do not immediately tighten everything. First ask whether your budget is describing your life accurately.